Commonwealth warns oil boom is putting US$43.5B in assets at flood risk
Business
Finance
November 8, 2026
Share this article
Click to view full size
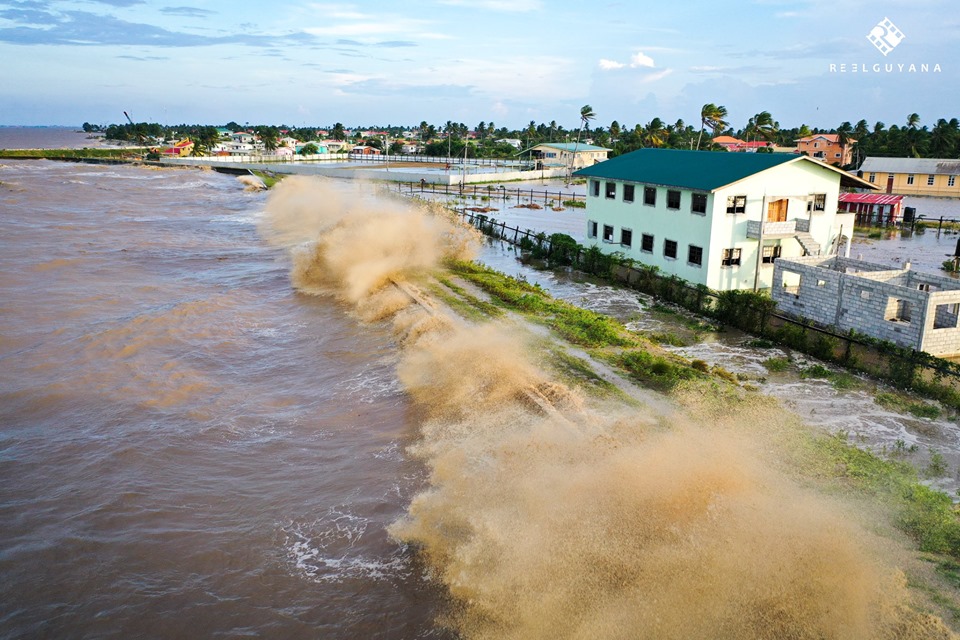
(Kaieteur News) – The Commonwealth has urged Guyana to set aside a portion of its national revenues to finance long-term coastal resilience, warning that the country’s oil-driven economic boom is placing billions of dollars in assets within an increasingly vulnerable coastal zone.
The aforementioned is stated in a study published in October that was commissioned by the Commonwealth Secretariat’s Climate Change and Oceans Directorate that focuses on Guyana, Kiribati, Papua New Guinea, Tonga and Tuvalu. The study noted that none of the five countries yet has adaptation governance and finance arrangements adequate enough to deal with the scale of the threat posed by rising sea levels.

Related coverageGuyana Opposition Figures Press Government for Relief as Living Costs Rise12 reports
The findings of the five-country case studies on sea level rise outline that in each case, the countries’ sea level rise is well above the global average of approximately 3.2–3.5mm per year. The rates range from roughly 5mm per year in Tuvalu and Kiribati to 7.3mm per year in Tonga and 4.7–10.2mm per year in Guyana.
Business
Finance
Need the bigger picture?
Share this article
Comments (0)
Download our mobile app
The portable companion to gazettE. Get notifications, track read articles, and more. The latest news from Trinidad and Tobago, in one place.