‘Guyana foreign currency burden deepens’
Business
Finance
September 17, 2026
Share this article
Click to view full size
(Kaieteur News) – Guyana’s foreign-currency debt has increased over the past year, with nearly 40 percent of the country’s public debt now owed in foreign currencies, leaving the Government more exposed to changes in exchange rates and the cost of servicing that debt.
According to the Ministry of Finance’s 2026 Mid-Year Report, foreign-currency debt accounted for 38.6 percent of total PPG debt at the end of June 2026, up from 35.1 percent a year earlier. The corresponding share of domestic-currency debt fell to 61.4 percent. The report identifies exchange-rate and interest-rate movements as the two major risks requiring close monitoring within Guyana’s debt portfolio.
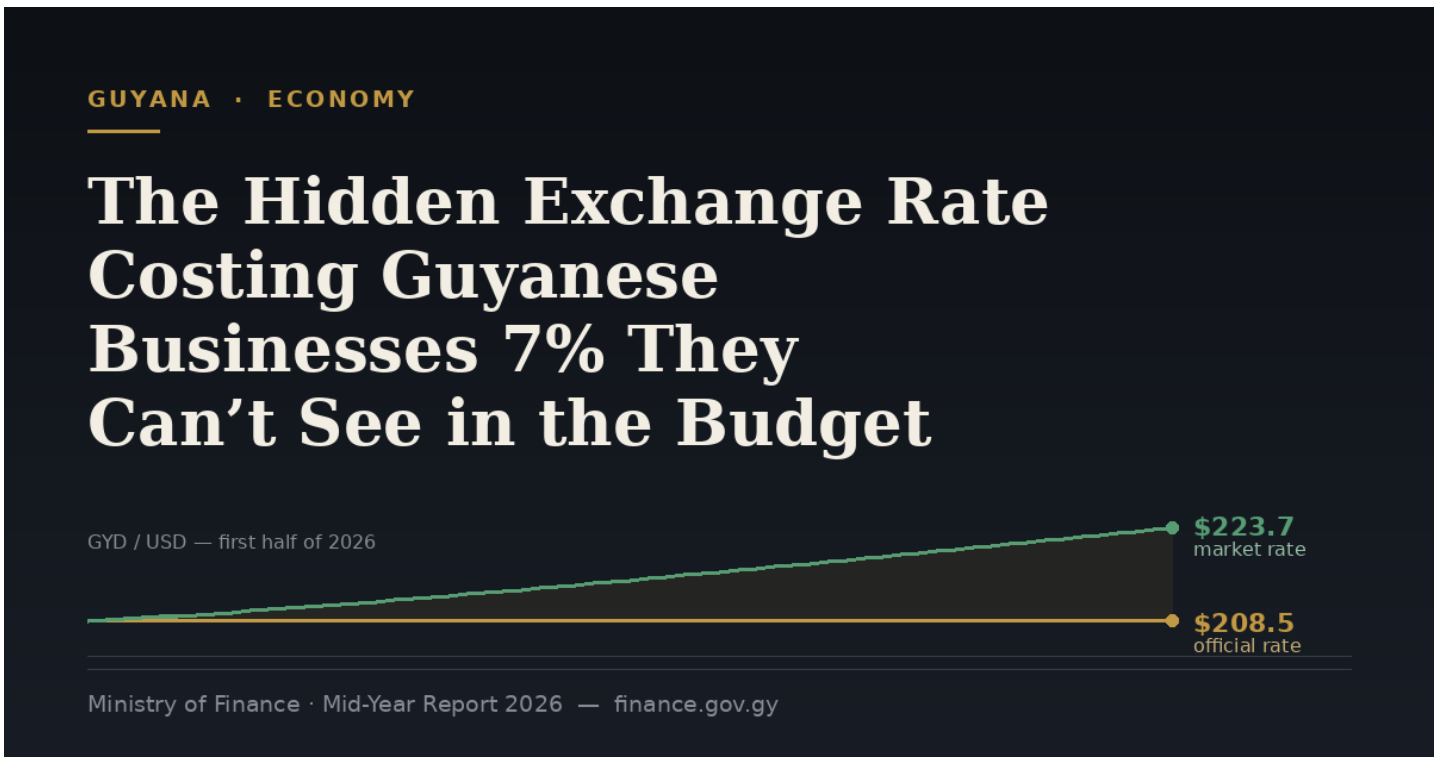
Earlier this week, President Irfaan Ali during a news conference said commercial banks purchased US$1.798 billion in foreign currency between January and June 2025, compared with US$2.279 billion during the corresponding period this year, an increase of 26.8%. Bank of Guyana foreign currency injections also increased from US$642 million to US$836 million over the same comparative periods. He said there will be significant foreign currency demand for the rest of the year, including US$385 million in October, US$400 million in November and US$436 million in December. According to the President discussions with commercial banks will take place to better understand the structure of that demand, including spending by large companies and the repatriation of profits by regional and multinational businesses.
Business
Finance
Need the bigger picture?
Share this article
Comments (0)
Download our mobile app
The portable companion to gazettE. Get notifications, track read articles, and more. The latest news from Trinidad and Tobago, in one place.